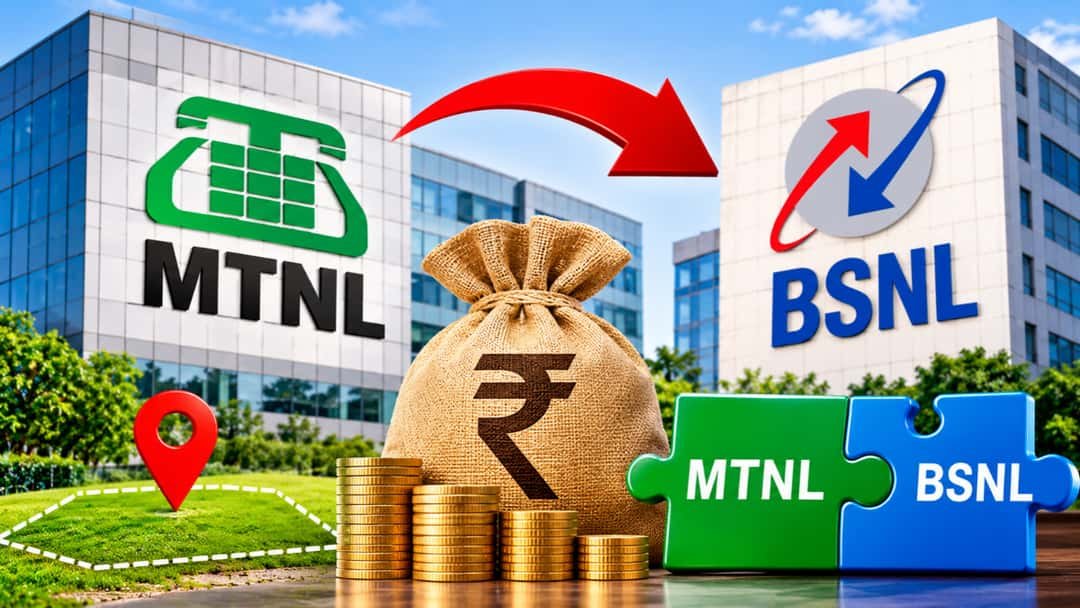
New Delhi: The government’s latest push to monetise Mahanagar Telephone Nigam Limited (MTNL)’s surplus land and buildings has once again brought the long-pending MTNL-BSNL merger into sharp focus. An Inter-Ministerial Group on Asset Monetisation has recommended Cabinet approval for selling a fresh tranche of non-core assets valued at ₹1,100 crore. The move aims to reduce MTNL’s liabilities, which exceed ₹40,000 crore (and rise further when sovereign-guarantee bonds are included).
MTNL, which serves Delhi and Mumbai, has been operated by Bharat Sanchar Nigam Limited (BSNL) under a service agreement since January 2025. The formal merger between the two state-owned companies was stalled years earlier precisely because of MTNL’s heavy debt burden.
Larger Monetisation Plans
Officials have indicated that up to ₹6,000 crore could be raised from MTNL assets in the current financial year (FY27), including five Mumbai properties worth about ₹4,000 crore that have already cleared the Alternative Mechanism. Plans for around ₹9,000 crore of MTNL land and building sales in FY28 are also under discussion.
The National Land Monetisation Corporation will handle the sales process. Proceeds are intended to help service debt and meet other obligations.
Why Asset Sales Alone Are Not Enough
Several recent analyses and editorial comments highlight a core concern: selling land cannot replace a clear decision on MTNL’s long-term role.
- Customers in Delhi and Mumbai still need reliable telecom services.
- Treating the company mainly as a real-estate portfolio risks leaving the underlying business problems unresolved.
- A pure service-agreement model with BSNL leaves open questions about accountability, investment priorities, and the future structure of the two PSUs.
Commentators argue that any monetisation programme should be linked to a published transition plan covering debt reduction, service standards, and the eventual corporate relationship between MTNL and BSNL. A revived merger, properly structured and timed, could create a stronger public-sector player capable of competing in today’s market rather than simply transferring problems from one balance sheet to another.
Strategic Context
Telecom remains a strategic sector, so outright privatisation of MTNL is considered unlikely. BSNL itself has shown some operational improvement but continues to report losses. Combining the two entities under a time-bound roadmap, while using asset-sale proceeds to clean up the balance sheet, is increasingly seen as a more coherent path than continuing with the current interim arrangement.
The ₹1,100 crore recommendation is therefore more than a routine asset sale. It has reopened a larger debate: whether the government will use the cash from land and buildings to build a viable, competitive public telecom presence, or whether MTNL will gradually shrink into little more than a vehicle for property disposals.
A clear service roadmap and a fresh, realistic look at the merger remain the missing pieces.