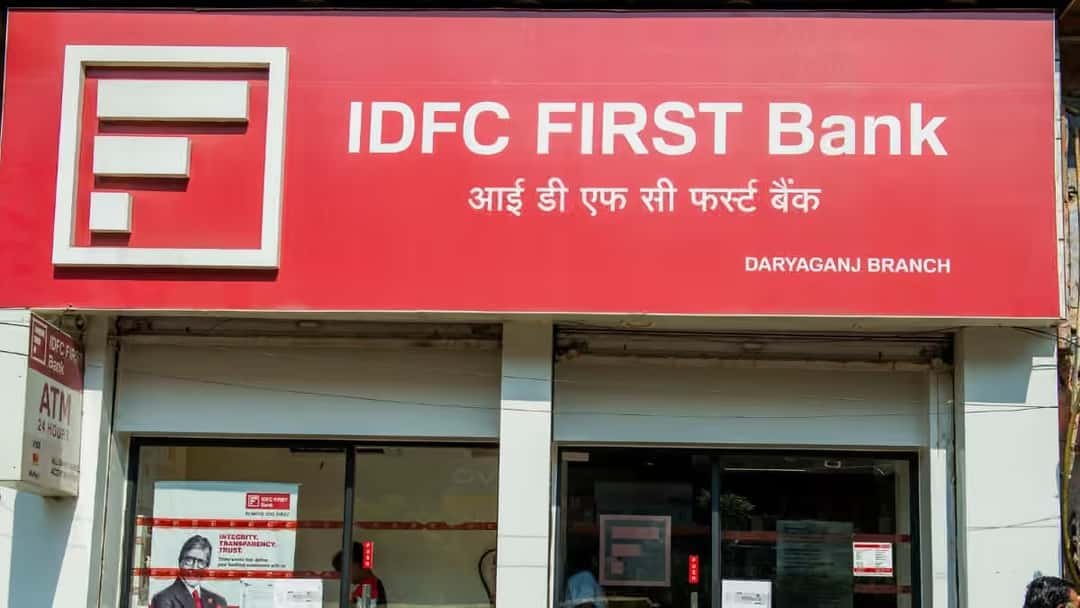
Mumbai : Brickwork Ratings has reaffirmed its BWR AA+/Stable rating on IDFC FIRST Bank Limited’s outstanding Non-Convertible Debentures (NCDs), aggregating ₹406.90 crore. The bank disclosed the rating reaffirmation to the stock exchanges in accordance with regulatory requirements.
The outstanding amount of the rated NCDs has declined from ₹621 crore to ₹406.90 crore following redemptions upon maturity. The reaffirmation indicates that Brickwork Ratings continues to maintain its existing assessment of the bank’s creditworthiness for the rated debt instruments, with the outlook remaining Stable.
Business Growth and Deposit Strength Support Rating
Brickwork Ratings highlighted several factors supporting the rating, including the bank’s steady business growth, strong deposit franchise, comfortable capital position and healthy asset quality.
IDFC FIRST Bank’s total business reached ₹6.17 lakh crore as of June 30, 2026, reflecting the scale of its banking operations and continued business expansion.
The bank also benefits from a strong deposit base, with retail deposits accounting for approximately 80% of its total deposits. A substantial retail deposit base is an important factor in supporting funding stability and reducing dependence on more concentrated sources of funding.
CASA Deposits Grow 25% Year-on-Year
The bank recorded a 25% year-on-year increase in Current Account and Savings Account (CASA) deposits, taking the total to ₹1.58 lakh crore. Its CASA ratio stood at 50.8%.
CASA deposits are an important component of a bank’s funding structure because current and savings accounts generally provide a relatively low-cost source of funds compared with certain other deposit categories.
The growth in CASA deposits and the high share of retail deposits were among the key strengths highlighted by Brickwork Ratings in reaffirming the bank’s debt rating.
Capital Adequacy Remains Comfortable
Brickwork Ratings also noted the bank’s capital position as a supporting factor.
As of June 30, 2026, IDFC FIRST Bank reported a Capital to Risk-Weighted Assets Ratio (CRAR) of 15.05%, while its Common Equity Tier 1 (CET-1) capital ratio stood at 13.33%.
These capital adequacy indicators are important measures of a bank’s ability to absorb potential losses and support its lending and business activities while meeting applicable regulatory capital requirements.
The bank had also raised ₹7,500 crore through Compulsorily Convertible Preference Shares (CCPS) in the second quarter of FY2026. These instruments were subsequently converted into equity, strengthening the bank’s capital base.
Asset Quality Remains Healthy
Asset quality was another factor supporting the rating reaffirmation. According to the disclosed information, the bank’s Gross Non-Performing Assets (GNPA) ratio remained below 2%, while its Net Non-Performing Assets (NNPA) ratio was below 1%.
GNPA represents the proportion of gross advances classified as non-performing, while NNPA reflects the remaining non-performing assets after accounting for provisions and other applicable adjustments.
Maintaining these ratios at relatively contained levels is an important indicator of a bank’s loan portfolio performance and credit-risk management.
Stable Outlook Maintained
With the rating reaffirmation, Brickwork Ratings has retained the Stable outlook on the bank’s rated NCDs. The rating assessment reflects the factors cited by the agency, including business growth, deposit mobilisation, capital adequacy and asset quality.
The outstanding rated NCDs currently stand at ₹406.90 crore, following repayments on maturity that reduced the amount from the earlier ₹621 crore.
The disclosure was made under Regulation 30 of the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015, which governs disclosures of material events and information by listed entities.
The rating reaffirmation provides an updated assessment of IDFC FIRST Bank’s outstanding rated debt instruments. However, a credit rating is an assessment of credit risk and should not be interpreted as a guarantee of repayment or as a recommendation to buy or sell the bank’s shares or debt securities.